
Why are you still chasing paper trails whilst the rest of the world moves at the speed of light? In 2026, the average mortgage closing time remains a sluggish 38.2 days; this leaves buyers trapped in a loop of manual document gathering and repetitive data entry. You likely feel the frustration of opaque underwriting processes that turn a simple property dream into a weeks-long ordeal of uncertainty. It's exhausting to fear a rejection based on an outdated credit model when a smart mortgage application could verify your real-time financial behaviour in seconds.
A smart mortgage application is a high-tech strategy that puts you in control. By utilising AI-driven data and direct API links, you can bypass legacy banking delays and force lenders to compete for your business with instant pre-approvals. This guide reveals how to build a single digital dossier that integrates your property search with real-time lending data. We'll show you how to leverage VantageScore 4.0 and trended credit trajectory to secure a faster, more accurate approval that reflects your true financial power.
We'll explore the transition from static paperwork to seamless digital dossiers and explain how PropertyZoom’s AI ecosystem eliminates the risk of down-valuation. Prepare to transform your home-buying journey into a streamlined, transparent process that delivers results in days, not months.
Key Takeaways
- Replace static PDF forms with a pre-verified digital dossier that uses direct API links for instant income and dividend verification.
- Discover the five essential pillars of a smart mortgage application to ensure your financial identity is optimised for AI-driven underwriting.
- Learn how to audit your digital footprint and configure Open Banking permissions to present a transparent, low-risk profile to modern lenders.
- Leverage ZEBA AI within the PropertyZoom ecosystem to predict your mortgage eligibility and align property search with real-time lending data.
- Understand the shift from single-score assessments to behavioural risk profiling that reduces the chance of manual delays or unexpected down-valuations.
Why Traditional Mortgages Are Obsolete in 2026
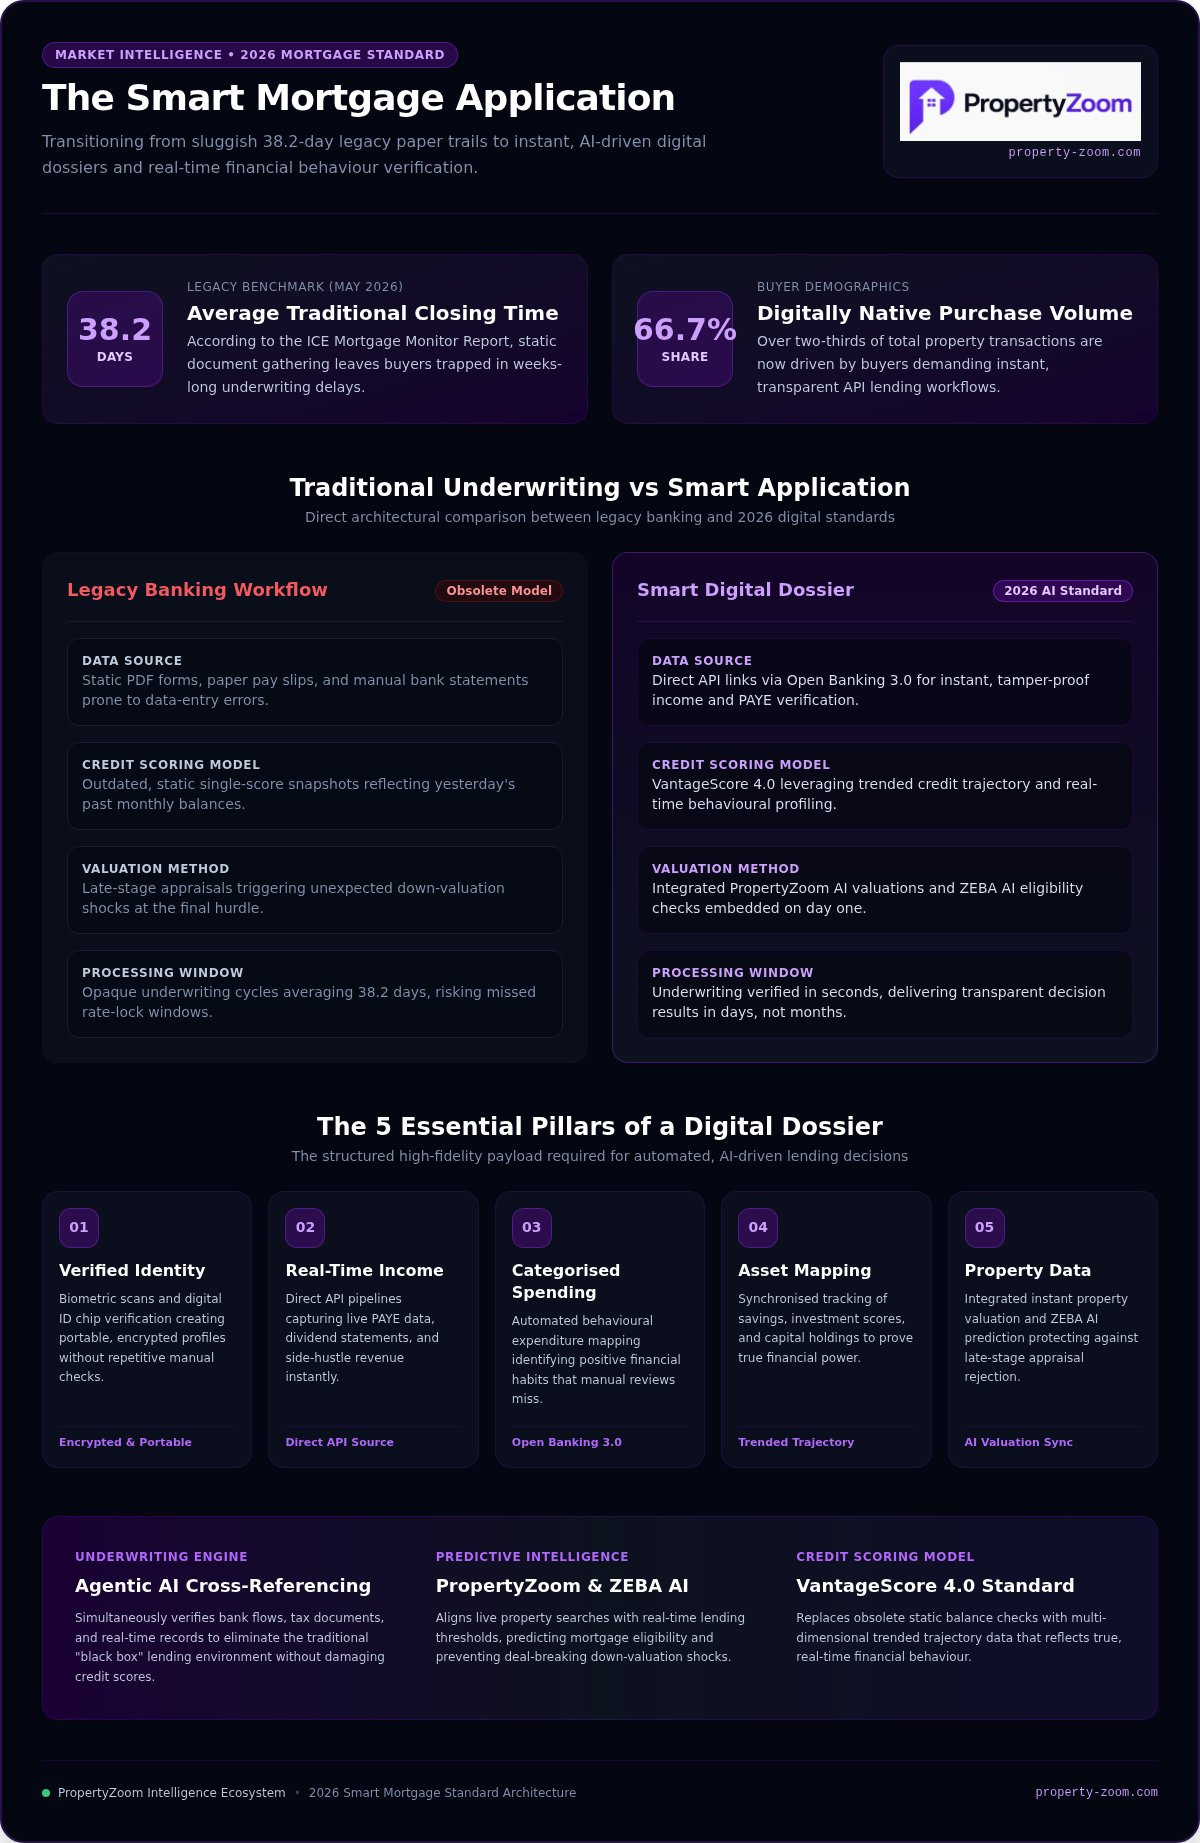
The 2026 property market moves too fast for static PDFs and paper trails. Traditional lenders still rely on a snapshot of your past, but a smart mortgage application focuses on your real-time financial behaviour. Static digital forms aren't enough anymore. They're just digitised versions of a broken system. You need a process that connects directly to your bank account via Open Banking 3.0 to provide instant proof of income and expenditure. Without this real-time link, you're essentially providing yesterday's news to a lender who needs today's certainty.
The Problem with Manual Document Verification
Document fatigue is a silent deal-killer. When you manually gather pay slips and bank statements, you risk human error and significant delays. According to the ICE Mortgage Monitor Report from May 2026, the average closing time sits at 38.2 days. In a competitive market, these legacy banking delays often mean losing your favourite property to a faster buyer. Traditional mortgage underwriting process methods are now viewed as a red flag. They suggest a lack of efficiency that can lead to higher interest rates or missed rate-lock windows. Digital friction doesn't just slow you down; it costs you money. Lenders now use AI to spot inconsistencies in seconds, meaning any manual error in your data entry can trigger an immediate rejection.
Defining the 2026 Smart Mortgage Standard
A true smart mortgage application integrates property search data directly into the lending workflow. It uses agentic AI to cross-reference tax records and bank flows simultaneously. This removes the "black box" feel of old-school lending. You get real-time eligibility checks that don't damage your credit score. Modern lenders prioritise transparency and speed because digitally native buyers now account for 66.7% of all purchase volume. They want to see your trended credit trajectory, not just a single monthly balance. By using platforms like PropertyZoom, you ensure that AI valuations and investment scores are part of your dossier from day one. This alignment prevents the "down-valuation" shock that often derails traditional applications at the final hurdle. Speed is no longer a luxury. It's the benchmark for a successful transaction.
The Smart Mortgage Application Template: Your Digital Dossier
Forget the era of filling out repetitive questionnaires. A smart mortgage application in 2026 relies on a pre-verified digital dossier. This is a secure data payload that replaces the traditional stack of paperwork. It acts as a bridge between your financial life and the lender's algorithm, providing a high-fidelity view of your creditworthiness. To succeed, your dossier must be built on five pillars: verified identity, real-time income, categorised expenditure, asset mapping, and property data. By organising these layers before you even view a house, you eliminate the friction that causes applications to stall.
Income verification has evolved beyond the monthly pay slip. Modern systems use APIs to pull data directly from PAYE records, dividend statements, and side-hustle platforms. This direct-source data is tamper-proof and provides underwriters with instant certainty. Even the CFPB loan application packet guide emphasises the need for comprehensive records, but the 2026 standard requires these records to be live. Your expenditure profile is equally automated. AI categorises your spending behaviour, identifying positive patterns that manual reviews might overlook. Attaching an instant property valuation to your dossier ensures the lender sees the asset's value immediately, reducing the risk of a late-stage rejection due to a low appraisal.
Step 1: The Identity and Credit Layer
Biometric ID verification has made manual passport checks obsolete. A quick face scan and a chip-read of your ID create a secure, encrypted profile. Your credit insights also update in real-time whilst you shop for homes, reflecting your latest financial moves instantly. A Digital ID is the secure and portable foundation of every 2026 lending decision. It allows you to move between lenders without restarting your identity checks from scratch.
Step 2: Asset and Liability Mapping
Your dossier should automatically pull data from savings accounts, ISAs, and even crypto-wallets to show a full picture of your wealth. AI identifies low-risk financial patterns, such as consistent saving habits or diverse asset holdings, that traditional human reviewers often miss. You can also link your investment scores to prove the long-term viability of the property you intend to buy. To get started, you can organise your search and mortgage data through a single integrated platform for maximum efficiency.
AI Credit Assessment vs Manual Underwriting: A Comparison
Manual underwriting is a relic of a paper-heavy past. Whilst a human processor might spend weeks auditing physical bank statements and calculating debt-to-income ratios, AI completes these tasks in minutes. This shift isn't just about speed; it's about the depth of the analysis. A smart mortgage application leverages agentic AI workflows to cross-reference your financial trajectory over 24 months, rather than judging you on a single monthly snapshot. This approach is particularly beneficial for the millions of non-traditional earners amongst the modern workforce, such as freelancers and contractors, whose income may fluctuate but remains consistently strong.
Transparency is the primary concern for many applicants facing automated systems. The "Black Box" problem, where a computer says "no" without explanation, is being dismantled by strict regulatory oversight. Lenders are now required to provide human-explainable reasons for every automated decision. Citing CFPB guidance on algorithmic credit decisions, modern platforms must ensure that their models are interpretable and free from hidden bias. This ensures your smart mortgage application is judged on merit and clear data, not opaque calculations that you cannot challenge.
How AI Evaluates Your Financial Behaviour
AI looks for financial resilience. Instead of just checking if you can afford a payment today, it analyses how you manage recurring costs and subscription services. These patterns provide a predictive view of your future reliability. You can further strengthen your case by integrating data from an AI property search platform. By showing that your chosen property has a high investment score and stable valuation history, you provide the lender with additional confidence in the collateral, not just your credit score.
Reducing the Risk of Down-Valuation
A significant percentage of property transactions fail because of the "valuation gap" between the offer price and the lender's appraisal. Smart applications solve this by using automated valuation models (AVMs) that align your offer with the lender's internal data before you commit. This synergy between digital surveying and mortgage approval ensures that the price you pay is supported by real-time market metrics. By removing the guesswork, you protect your deposit and keep the transaction moving toward a successful close. This integrated approach turns the lending process from a hurdle into a streamlined, data-driven journey.
How to Organise Your Data for Instant Approval
Preparation is the fundamental difference between an instant approval and a frustrating manual audit. You must audit your digital footprint before the lender's algorithm does. In 2026, Open Banking 3.0 standards allow you to select granular levels of access for lenders. Don't just grant blanket permission; share only what is necessary to prove your income and financial stability. Syncing your property search with your mortgage portal creates a seamless data loop. When you link your favourite listings, the lender can run automated pre-checks on the specific asset. This proactive approach reduces the time spent on conditional approvals and ensures your smart mortgage application remains at the front of the queue.
Optimising Your Expenditure Profile
The 3-month rule is more critical than ever in a high-tech lending environment. AI underwriters look for consistent financial behaviour over a rolling quarter to predict your future reliability. You should categorise your spending into discretionary and essential groups to present the clearest possible picture of your disposable income. If you have high subscription costs, consider if they reflect your long-term resilience or if they might be flagged as unnecessary liabilities. Pre-linking your digital conveyancing and property legal services ensures that once the AI gives the green light, the legal process starts immediately. This removes the dead time that often follows a traditional mortgage offer.
Selecting the Right Smart Lender
Not all lenders are created equal in the 2026 landscape. You should compare banks based on their AI-readiness and approval speed rather than just the headline interest rate. A low rate is useless if a legacy manual process causes you to miss a completion deadline and lose your rate lock. Use PropertyZoom to identify lenders that accept digital property surveying data directly into their underwriting engine. This integration allows for a smart mortgage application to proceed without waiting for a physical valuer to visit the property, potentially saving you weeks of uncertainty.
Before you hit the final submit button, use an AI-checker to spot potential inconsistencies in your dossier. Even a small mismatch between your digital ID and your bank account address can trigger a manual review flag. Precision is your greatest asset in a digital workflow. Once your data is organised and your lenders are shortlisted, you can apply for your smart mortgage through our integrated portal to secure your rate today.
Leveraging PropertyZoom for a Seamless Lending Experience
PropertyZoom transforms the fragmented property market into a unified ecosystem. A smart mortgage application shouldn't exist in a vacuum; it needs to live where you search, value, and secure your home. By housing every stage of the journey on one platform, we eliminate the data silos that cause traditional banking delays. You no longer need to export data from one site to another. Instead, your verified property search data flows directly into your lending dossier. This creates a high-velocity workflow that can condense the property transaction time from the industry average of 38 days to under 14 days, representing a reduction of up to 60%.
The PropertyZoom Ecosystem Advantage
The platform integrates legal conveyancing, surveying, and mortgages into a single environment. This creates a Trust Loop for lenders. When a lender receives your smart mortgage application, they see a pre-verified package that includes AI-driven valuations and investment scores. This transparency reduces their perceived risk and speeds up their decision-making process. ZEBA AI acts as your high-tech assistant throughout this journey. You can use conversational search to ask specific questions about affordability or investment potential. ZEBA AI provides data-backed answers in seconds, allowing you to move forward with confidence. Our integrated legal and surveying partners are already synced with our data standards, ensuring the final closing is just as fast as the initial approval.
Your Next Steps to a Smarter Mortgage
Your journey to a faster home purchase starts with preparation. You should begin building your digital dossier today by organising your financial identity and enabling Open Banking permissions. Use our integrated investment scores to your advantage during negotiations. These scores prove the long-term viability of the asset, giving you a stronger position when discussing terms with lenders or sellers. We connect you with pre-vetted brokers who specialise in these modern lending models and understand the value of a data-driven application. Don't let legacy banking processes dictate your timeline. Take control of your data and secure your future home with a process designed for the 2026 market. Start your smart mortgage journey with PropertyZoom today.
Secure Your Future in the 2026 Property Market
The era of waiting weeks for a manual underwriting decision is over. By building a pre-verified digital dossier and leveraging real-time data, you move from search to completion with total clarity. Success in this high-velocity market requires a smart mortgage application that integrates every stage of the journey. You don't have to navigate this alone; the right technology turns a complex hurdle into a streamlined advantage.
PropertyZoom is powered by ZEBA AI for instant eligibility checks, ensuring you never waste time on properties that don't fit your profile. Our ecosystem is integrated with the UK's leading digital conveyancers and includes real-time property investment scores to give you a competitive edge. This unified approach removes the traditional barriers to homeownership, providing the speed and transparency you deserve. It's time to leave legacy banking delays behind and embrace a more intelligent way to buy.
Start your Smart Mortgage Application with PropertyZoom and take the first step toward your new home today.
Frequently Asked Questions
What exactly makes a mortgage application 'smart' in 2026?
A smart application replaces static documents with real-time data integration. It uses secure APIs to pull your income, expenditure, and identity data directly from the source. Instead of manual underwriting, it employs agentic AI workflows to analyse your financial behaviour over a 24-month period. This ensures lending decisions are based on your actual credit trajectory rather than a single, outdated score. It is a faster, more accurate way to prove your creditworthiness to modern lenders.
Is my financial data safe when using an AI-powered application?
Your data is protected by bank-grade encryption and secure Open Banking protocols. Unlike traditional paper-heavy processes where documents are often emailed or posted, a smart application uses secure links to transfer data directly between financial institutions. This significantly reduces the risk of document fraud and identity theft. You maintain full control over your information and can revoke access at any time through your digital banking app or the platform interface.
How much faster is a smart mortgage application compared to a traditional one?
A smart application can condense the mortgage process from the current industry average of 38.2 days to under 14 days. Pre-approvals that used to take several business days now happen in less than an hour. This is because the AI verifies your income and assets instantly via direct API links. This speed gives you a massive advantage in competitive markets, allowing you to secure rate locks faster and reduce the risk of losing your favourite property.
Can I use a smart application if I am self-employed or have a complex income?
AI-driven models are often more effective for complex earners than traditional manual audits. These systems are designed to look at your total financial resilience by analysing 24 months of cash flow, dividends, and side-hustle income via Open Banking. This builds a comprehensive profile that rigid, old-school underwriting might miss. It helps freelancers and contractors get approved based on their actual earnings rather than falling foul of outdated and inflexible lending criteria.
What is Open Banking and why is it required for a smart mortgage?
Open Banking is a secure technology that allows you to share your financial data with trusted providers. It is the engine behind every smart mortgage application because it provides instant, tamper-proof proof of your income and spending habits. Instead of you manually downloading and uploading PDF statements, the lender receives a verified data feed. This eliminates human error and speeds up the risk assessment process whilst ensuring the lender has the most current information.
Will a smart mortgage application help me get a better interest rate?
Using a smart mortgage application can make you a more attractive prospect to lenders. By providing a pre-verified digital dossier, you reduce the lender's administrative costs and risk profile. This efficiency often allows them to offer more competitive rates. Additionally, because the process is so fast, you can secure a rate lock early. This protects you from market fluctuations that might occur during the weeks a traditional manual application would take to process.
Do I still need a mortgage broker if I use a smart application?
You don't strictly need one, but many buyers prefer a hybrid approach. PropertyZoom connects you with pre-vetted brokers who specialise in AI-driven lending models. These professionals use the data from your digital dossier to find the best deals across multiple lenders. The technology handles the data gathering and verification, whilst the broker provides strategic advice. This combination ensures you get the most efficient process and the most suitable financial product for your needs.
What happens if the AI valuation is different from the lender's valuation?
PropertyZoom uses ZEBA AI to provide instant valuations designed to align with lender data. If a discrepancy occurs, our integrated investment scores help you provide additional context to the lender. Because our valuations use the same algorithmic standards as many modern banks, the risk of a down-valuation is significantly reduced. If the lender's final appraisal differs, your digital dossier already contains the supporting data needed to appeal the decision or renegotiate the offer price with the seller.


